Voltmax Energy Solutions in Luxembourg
Reduced VAT · Luxembourg
3% VAT instead of 17% for your home
Solar panels on a private home are invoiced at 3% VAT. Renovation work on a main residence that is at least ten years old can qualify for the same super-reduced rate – a saving of up to €50,000 per dwelling. Here is what is covered and how to apply.
At a glance
The super-reduced VAT rate in four numbers
Luxembourg’s standard VAT rate is 17%. For housing, the State applies a super-reduced rate of 3% – automatically for solar panels, and on approval or refund for construction and renovation work.
3%
VAT rate on solar panels for private homes and on eligible housing work, instead of 17%.
€50,000
Maximum tax benefit per dwelling created or renovated.
10 years
Minimum age of the building when renovation work starts.
2 years
The home must stay a main residence for two years after the work, or the benefit is reclaimed.
Solar panels
Solar panels: 3% without any paperwork
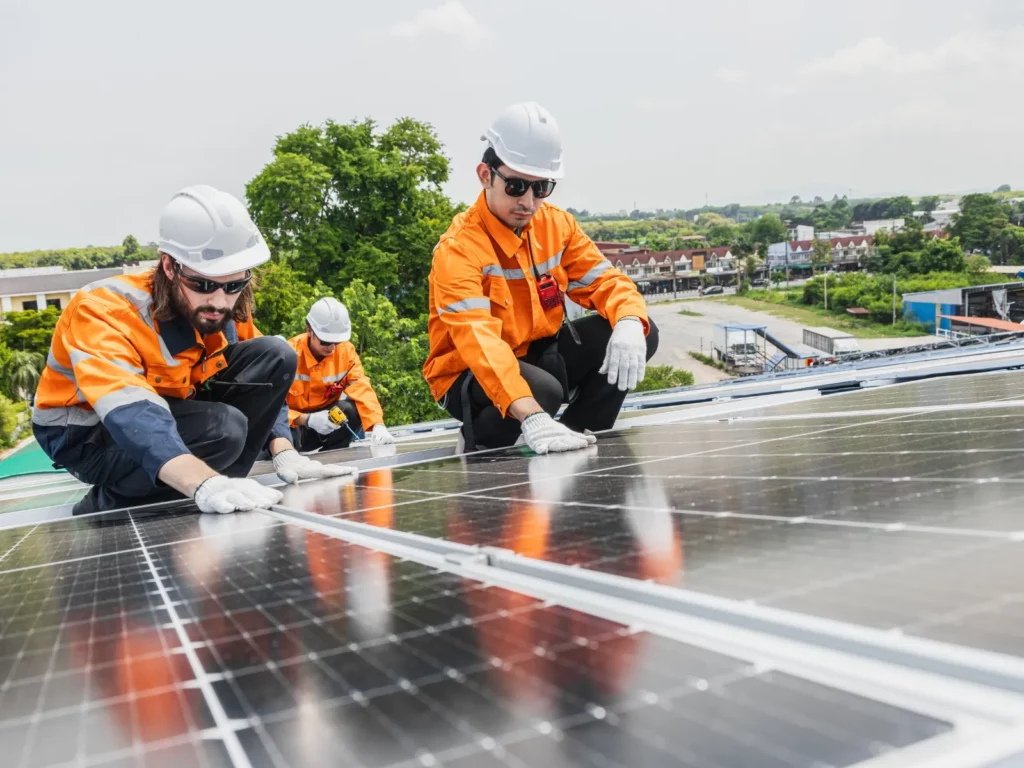
The supply and installation of solar panels on private dwellings are taxed directly at the 3% super-reduced rate. Your installer simply invoices 3% – no prior approval is needed, and this does not count towards the €50,000 housing ceiling.
- Covers the panels, mounting rails, DC and AC cabling, inverter, electrical protection, the bidirectional meter and the installation work
- Applies to solar panels on private dwellings, invoiced directly by the installer
- A home battery is not part of this solar panel rule – ask us how it is invoiced in your project
- Combines with the Klimabonus and municipal aid
The Klimabonus is calculated on the system, not on the VAT – the lower VAT simply reduces what you pay.
Renovation
Renovation work on your main home
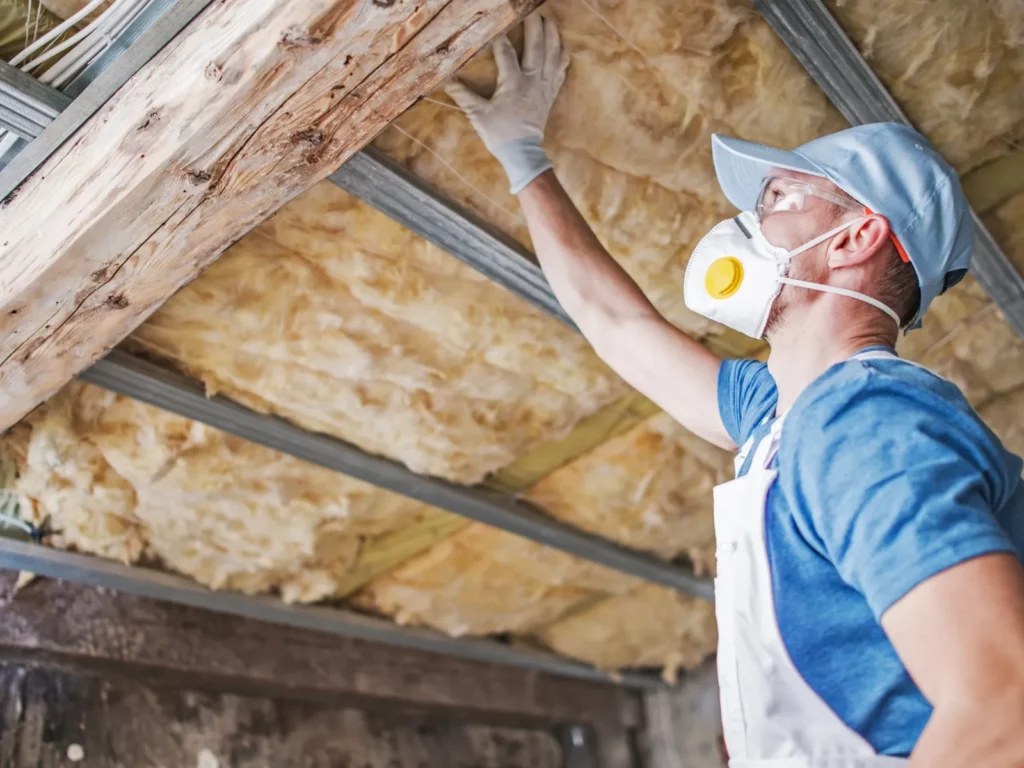
Construction and renovation work on a dwelling used as a main residence can be invoiced at 3%. For renovation, the building must be at least ten years old when work starts, and the work must be completed within two years of starting. The home can be lived in by you or by a tenant.
- Roofing and waterproofing, facades and insulation
- Windows and doors
- Heating installations and controlled ventilation
- Solar thermal collectors and electrical installations
- Sanitary fittings, plastering, floor and wall coverings, painting
Not covered: furniture and fitted kitchens, home automation and alarms, air conditioning, garden landscaping, architect and notary fees, interior blinds – and anything not on the official list.
How it works
Two ways to get the 3% rate
Direct application
Before work starts, your contractor asks the VAT administration (AED) for approval, and you countersign. Once approved, the invoices show 3% straight away.
Refund afterwards
Paid 17%? Claim the difference back from the AED: the claim must exceed €3,000 excl. VAT, cover at least six months, with each invoice above €1,250 excl. VAT.
Five-year deadline
The right to a refund lapses five years after 31 December of the year the VAT relates to.
Two years as a main home
From 1 January after the work, the home must be a main residence for two years. Otherwise the benefit is reclaimed with interest.
Requests can be made online through MyGuichet.lu (with a mandate from you when the contractor files it) or with the paper form. If three quarters or less of the building is used as a main residence, the benefit is reduced proportionally.
An example
What 3% instead of 17% means in euros
€8,400 saved
On €60,000 of renovation work (excl. VAT): €1,800 VAT at 3% instead of €10,200 at 17%.
€2,800 less
On a €20,000 solar installation (excl. VAT): €600 VAT at 3% compared with €3,400 at the standard rate.
€50,000 ceiling
The housing benefit per dwelling is capped – enough for roughly €357,000 of work excl. VAT.
Illustration only. The VAT administration decides which work qualifies. Sources: guichet.lu, “Remboursement de la TVA ou application directe du taux super-réduit” (updated 10 November 2025); Klima-Agence FAQ on reduced VAT for photovoltaics.
FAQ
Questions about reduced VAT
Does the 3% rate apply to a heat pump?
Heating installations are on the list of eligible renovation work. A heat pump installed in a home at least ten years old and used as a main residence can therefore qualify, through the direct application or the refund. For a newly built home, the rules for creating a dwelling apply.
Do I need to do anything for solar panels?
No. Solar panels on private dwellings are invoiced directly at 3% by the installer, without any approval, and they do not count towards the €50,000 housing ceiling.
Does it work for a home I rent out?
For renovation, yes – the home can be the main residence of a tenant. You declare it in the request for direct application.
What does the €50,000 limit mean?
It is the maximum VAT saving per dwelling created or renovated. With a 14-point difference between 17% and 3%, it corresponds to roughly €357,000 of eligible work excluding VAT.
What happens if I sell the home soon after the work?
The home must be used as a main residence for two years from 1 January after the work is completed. If it is used for other purposes, left empty or sold before then, the VAT benefit is reclaimed with interest.
Can I combine reduced VAT with the Klimabonus?
Yes. Reduced VAT lowers the price you pay; the Klimabonus, municipal aid and the Topup social are subsidies on top. The climate loan can finance what remains.
Combine your support
Other help for the same project
Reduced VAT combines with the subsidies and the climate loan. Each has its own rules and application.
Klimabonus
The state subsidy for solar panels, batteries, heat pumps and insulation.
Your commune
Most communes add their own subsidy. See the official figures for all 100 communes.
Topup social
Households below the median income can receive 10–100% extra on top of their Klimabonus.
Climate loan
A bank loan for the rest of the investment, with a 1.5% interest subsidy from the State.
Have questions?
Let’s check which VAT rate applies
Tell us about your home and your project. A Voltmax advisor will tell you which VAT rate applies and handle the approval request with you – free and without obligation.
- VAT, subsidies and remaining cost checked together
- Offer with the pre-financing option included
- Call us on +352 26 33 86